Reverse Mortgages Gain Attention in Canada as Homeowners Explore Retirement Financing Options
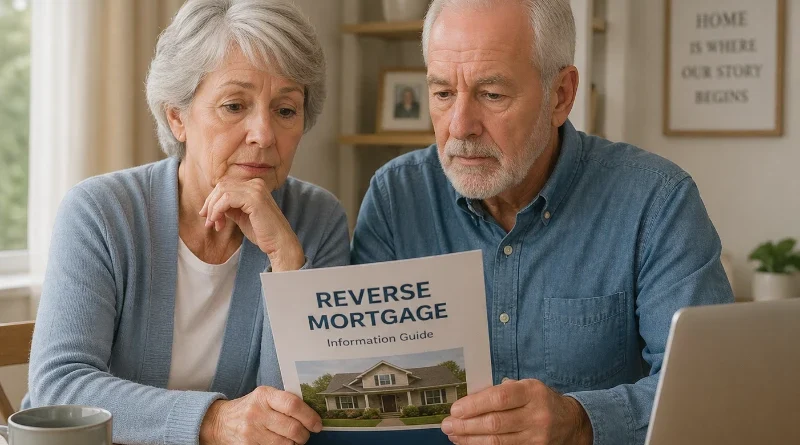
Reverse mortgage rates in Canada are gaining attention as older homeowners search for practical ways to strengthen their retirement finances. With rising living expenses and changing economic conditions, many Canadians are exploring how their home equity can provide additional financial flexibility without requiring them to sell their properties.
However, choosing the right reverse mortgage requires careful consideration. Interest rates, repayment conditions, and long-term borrowing costs can significantly influence a homeowner’s financial future.
Reverse Mortgage Rates in Canada Attract Growing Interest
Canada’s housing market continues to play an important role in retirement planning. For many older homeowners, residential property represents one of their most valuable financial assets.
As a result, reverse mortgages have become an alternative for individuals seeking to access accumulated home equity while remaining in their homes.
Unlike traditional mortgages, these financial products generally do not require monthly principal or interest payments. Instead, the outstanding balance increases as interest accumulates.
This arrangement can provide immediate financial flexibility. Nevertheless, homeowners must understand how borrowing costs affect their remaining property equity.

Investment Opportunities Attract Real Estate Buyers
Bank-owned homes, foreclosure auctions, and distressed real estate assets are creating alternative investment opportunities for buyers seeking competitive property prices...
How Reverse Mortgages Work in Canada
Reverse mortgages are generally available to Canadian homeowners aged 55 and older who meet specific lending requirements.
Depending on their age, property value, and financial circumstances, eligible borrowers may access up to 55% of their home’s appraised value.
The funds can support various financial needs, including retirement expenses, home improvements, healthcare costs, or existing debt obligations.
Furthermore, the money received through a reverse mortgage is generally not considered taxable income because it represents borrowed funds rather than earnings.
However, homeowners remain responsible for property taxes, insurance, and maintenance throughout the loan period.
Comparing Reverse Mortgage Interest Rates
Interest rates remain a central consideration when evaluating reverse mortgage products in Canada.
Financial institutions may offer fixed or variable rates, depending on the selected loan structure and repayment terms.
Although fixed rates provide greater predictability, variable rates may fluctuate with broader financial market conditions.
In addition, reverse mortgage rates are typically higher than conventional mortgage rates. Consequently, accumulated interest can increase the total outstanding balance over time.
Homeowners should therefore compare interest rates, administrative fees, early repayment charges, and other contractual conditions before selecting a lender.
Canadian Lenders Expand Home Equity Financing Options
Several financial institutions operate within Canada’s reverse mortgage market, including HomeEquity Bank, Equitable Bank, Home Trust, and Bloom Finance.
These providers offer different financing structures designed to accommodate homeowners seeking additional retirement liquidity.
Competition among lenders gives consumers opportunities to evaluate alternative products. However, the lowest advertised interest rate does not necessarily guarantee the most favorable overall borrowing arrangement.
For this reason, financial advisers often recommend reviewing the total cost of borrowing rather than focusing exclusively on the initial interest rate.
Benefits and Financial Risks for Homeowners
Reverse mortgages can offer meaningful advantages for eligible Canadians.
Most importantly, borrowers can access part of their property wealth without immediately selling their homes. This flexibility may help retirees manage household expenses while maintaining residential stability.
Nevertheless, these products also involve financial risks.
Because interest accumulates over time, the outstanding debt may reduce the equity available when the property is eventually sold.
Additionally, repayment may become necessary when the homeowner permanently moves out, sells the property, or passes away, subject to the lender’s contractual conditions.
Therefore, evaluating the long-term implications is essential before entering into a reverse mortgage agreement.
Canada’s Housing Wealth Reshapes Retirement Planning
The increasing attention surrounding reverse mortgage rates in Canada reflects a broader transformation in how homeowners approach retirement financing.
Rather than viewing residential property exclusively as a place to live, some Canadians are considering home equity as a financial resource capable of supporting their later years.
Meanwhile, financial institutions continue developing lending products that respond to the needs of an aging population.
Ultimately, reverse mortgages may provide valuable financial flexibility, but informed decisions remain essential. Comparing interest rates, understanding repayment obligations, and protecting long-term home equity can help Canadian homeowners establish a more sustainable retirement strategy.
